In this issue
30 articles: 7 features and columns, 16 news, 7 regulation.
Features and columns · 7
January 2026 markets were driven by multiple overlapping themes rather than a single dominant story (see market review). This complexity played to hedge fund strengths. The HFRI Fund Weighted Composite Index rose 3.0%, marking a strong start to the year and reflecting broad-based gains across macro and equity strategies.
At times headlines suggest that the private credit market has not just hit peak levels but may be headed for a bit of a reckoning. The pundits see “signs of strain amid strong overheating risks” or the Fed issues warnings about stability as the market “rivals traditional bank lending.”…
When Simon Brewer interviewed Peter Håkansson, Chairman and Group CIO of East Capital, the conversation didn’t begin with an investment thesis or a chart on relative valuations. It began with something more revealing: geography, history and a blunt assessment of where the future is being built.
In a world relearning the value of energy security, Venezuela’s dysfunction is quietly reshaping geopolitics - and tightening U.S. leverage. Venezuela’s petroleum sector returned to the spotlight following the U.S. removal and detention of Nicolás Maduro in early January 2026, followed by a stated U.S. “oil quarantine” and selective licensing signals.
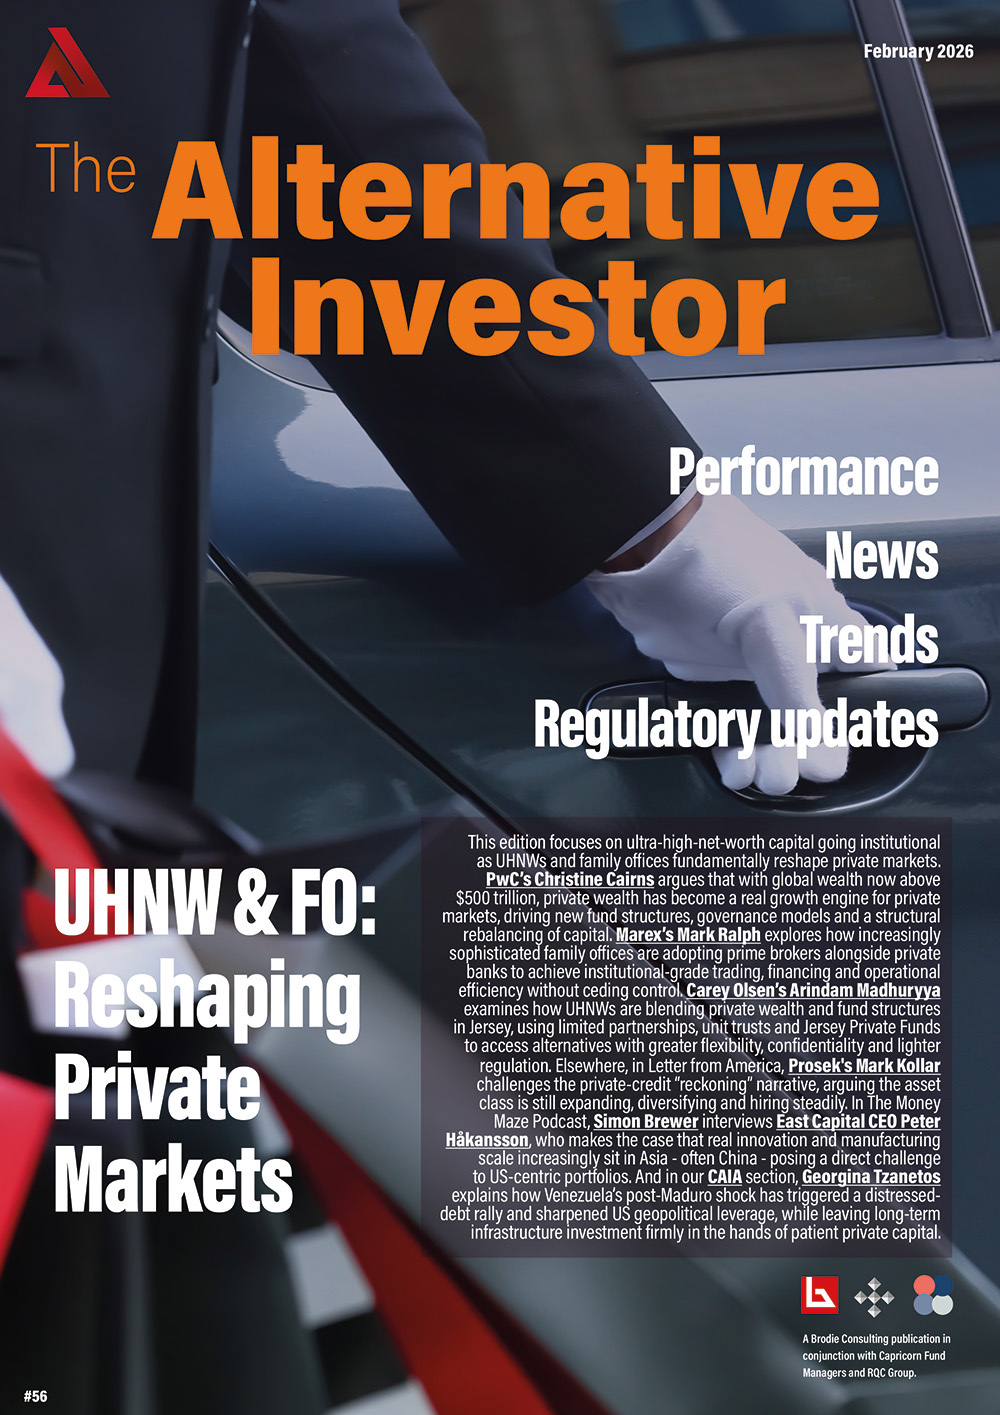
Global wealth has reached unprecedented levels. According to the UBS Global Wealth Report 2024, household wealth now exceeds USD 500 trillion globally and is expected to surpass USD 600 trillion by the end of the decade. But the real story for alternative asset managers is not the headline number — it is how this wealth is increasingly being mobilised and channelled into private markets.
For decades, ultra-high net worth individuals and family offices have relied on private banks and wealth managers for their capital markets activity. These relationships remain central to how families think about advice, governance and long-term stewardship of wealth.
Private wealth and investment funds are two of the mainstays of Jersey's financial services sector. In recent years, we have seen some convergence between the two sectors with two distinct themes of Ultra-High-Net-Worth Individuals (UHNWI) and family offices: (i) using Jersey limited partnerships and unit trusts; and (ii) using the Jersey fund regime to structure investments.
News · 16
Coller Capital closed its latest flagship secondaries vehicle, Coller International Partners IX, at the $12.5 billion hard cap, taking total commitments across the firm’s global private equity secondaries platform to around $17 billion. This is the largest fund in the firm’s 35-year history and one of the largest pools of capital ever raised in the private markets secondaries space.
The appetite for private credit exposure shows little sign of slowing, with Churchill Asset Management raising more than $16 billion for its senior lending programme. New York-based Churchill is a leading middle-market direct lender and an affiliate of Nuveen, with a core focus on providing senior secured loans to sponsor-backed companies across the US lower and core-middle markets.
KKR completed the fundraising for its second Asia-focused private credit vehicle, Asia Credit Opportunities Fund II (ACOF II), securing $2.5 billion in capital commitments. ACOF II invests across senior and junior credit, targeting companies in North Asia, Southeast Asia and Australia.
Goldman Sachs closed its latest co-investment vehicle, Private Equity Co-Investment Partners IV, at $2.8 billion, exceeding its original target. The fund invests alongside GSAM’s global private equity sponsors, targeting buyout and growth equity transactions across North America and Europe, with a particular focus on business services, technology, healthcare and industrials.
Hamilton Lane closed Hamilton Lane Infrastructure Opportunities Fund II (IOF II) at $1.9 billion, including related vehicles, targeting a mix of infrastructure secondaries and selective co-investments. Around 40% of the fund has already been deployed across 14 deals.
Sixth Street closed its third European direct lending fund at a hard cap of €3.75 billion, the San Francisco firm’s largest dedicated financing vehicle in the region to date. Including leverage, the fund is expected to deploy around €7 billion across a range of European middle-market financing opportunities.
AIP Management raised €2 billion in the first close of its fifth energy infrastructure fund, AIP V, putting the vehicle well on its way towards the €3 billion target. The fund will invest in renewable energy generation, storage and supporting infrastructure across Europe and North America.
Stafford Capital Partners final closed Stafford Infrastructure Secondaries Fund V (SISF V) at more than $1.1 billion, including associated vehicles, in its largest infrastructure fund to date. London-based Stafford specialises in niche private markets strategies, with infrastructure secondaries a core focus, with SISF V targeting interests in mature, high-quality infrastructure assets.
European mid-market specialist Apheon hit its €1.25 billion hard cap on its latest fund, Apheon MidCap Buyout VI (AMB VI). The fund continues Apheon’s strategy of backing founder-owned and family-run businesses across Western Europe, with a focus on operational value creation rather than financial engineering.
Madrid-based Arcano Partners raised €850 million for Arcano Secondary Fund V (ASF V), its fifth private equity fund. The fund focuses on control investments in profitable European mid-sized companies, with emphasis on operational improvement, buy-and-build strategies and sector specialisation.
Impact investor Lendable raised more than $300 million at the first close of two new blended-finance funds and is targeting to close above $500 million, marking a significant milestone for the London-based manager. The raise spans Lendable MSME Fintech Credit Fund II and Lendable Transportation and Energy Fund, lifting AUA toward $1 billion.
AIG and CVC announced a significant strategic partnership that could see up to $3.5 billion of AIG’s capital deployed across a range of private markets strategies. The US/ European tie-up reflects a growing appetite among global insurers for deeper, more customised relationships with large alternative asset managers.
CVC announced the acquisition of Marathon Asset Management, a move that materially strengthens CVC’s position in global credit. This is not positioned as just a peripheral bolt-on but a strategic expansion that fast-tracks CVC’s ambition to build a scaled, multi-strategy global credit franchise with deeper origination and broader institutional reach.
With consolidation increasingly the biggest game in town, EQT Group announced it is acquiring Coller Capital for up to $3.7 billion. This transaction comes on the heels of Coller’s successful close of its latest flagship secondaries fund, underscoring both the firm’s momentum and the strategic rationale for the deal.
Sport has rapidly emerged as private equity's next big hunting ground, with reports that KKR is looking to take a significant stake in Global Sport Group (GSG), the sports investment platform created by CVC, in a deal valued at around €2.75 billion.
The last week of February sees Miami turn into the world’s busiest hub for alternative finance during Miami Hedge Fund Week, with all the Florida trimmings. What started as a nascent meet-up is now the largest (and most important) convergence of hedge fund allocators, managers and intermediaries.
Regulation · 7
On 14 January 2026, EU and UK regulators announced a rare collaboration when the European Supervisory Authorities published a memorandum of understanding (“MoU”) with the UK’s Financial Conduct Authority (“FCA”), the Prudential Regulation Authority and the Bank of England, to enhance cooperation and oversight of critical third party providers.
The FCA is ploughing through its crypto roadmap. In December 2025, it launched a raft of proposals extending to crypto an approach similar to traditional finance, with clear information for consumers, proportionate requirements for firms and flexibility to foster innovation.
In an unusual case involving an oil consultant who was not an FCA-authorised person, the regulator on 16 January 2026 announced it had fined one Russel Gerrity £309,843 for using inside information to realise an illicit gain of £128,765.
Referencing its updated Enforcement Guide (“ENFG”), published June 2025 and revising its publicity policy for greater transparency, the FCA on 28 January 2026 launched the inaugural issue of Enforcement Watch: a new newsletter covering insights and themes from its enforcement work.
On 28 January 2026, the UK government completed a major reform of its sanctions compliance framework by transitioning to a single, consolidated list of all UK sanctions designations. From this date, the UK Sanctions List (“UKSL”), maintained by the Foreign, Commonwealth & Development Office, became the sole authoritative source for all UK sanctions listings.
On January 15, 2026, the Division of Investment Management staff updated its Marketing Compliance Frequently Asked Questions, providing additional clarity on two important aspects of Rule 206(4)-1 under the Advisers Act: the use of model fees when presenting net performance, and disqualification considerations for compensated testimonials and endorsements.
The SEC on 7 January 2026 proposed amendments to the rules that define which registered investment companies, investment advisers, and business development companies qualify as small entities for purposes of the Regulatory Flexibility Act ("RFA").
Receive The Alternative Investor each month, with news and features from across private capital.
Subscribe